Answer; Little. Each other mortgage loans make use of the gathered equity for the a house to help you receive funding because of their wanted demands. Truly the only improvement is a 2nd mortgage specifies the positioning out of the loan. Theoretically, a collateral Financial reputation shall be initial, second, third, next etc. Amansad Financial essentially simply render private mortgages in the first and you may 2nd position.
An easy way to Need Security From your home
So you have been paying on your financial for more than 10 years today. You’ve not taken out open mortgage loans (because you didn’t for instance the high interest rates) however has socked https://paydayloanalabama.com/camp-hill/ aside extra cash in order that at each and every home loan revival you’ve been able to make a much bigger reduction into the the principal you need to roll to your second financing. Today, in the event, the daughter is going to lead out over college, and you failed to some cut adequate to assist their that have university fees, costs, area and you can panel.
Or even your own spouse has received an analysis from Phase III cancers. The newest providers would-be invasive and expensive. He will need to take a lengthy hop out off absence off work, which sets you down seriously to a single earnings when you are and work out mortgage payments.
Or even you just had laid off of you to center government updates that you had stored for pretty much ten years. You have been looking for the history 9 days, however, little has arrived to suit your speciality. Your lady has actually left their particular occupations the entire time, thus you aren’t burning through your savings as quickly as you might otherwise be, but you will be that have a tough time to make finishes fulfill with the time being, and you run up some big balance into handmade cards, which hold a top interest rate.
A few of these are fantastic reasons why you should see how to capture guarantee regarding a home. If you are and come up with men and women home loan repayments continuously for many years, all that money is now seated in the home a lot like buck expense locked inside a massive container. If you need to utilize this currency for things big one to possess cropped right up such as the listing of situations significantly more than you’ll find different alternatives to help you take collateral regarding our house.
What is Best way For taking Collateral From your home
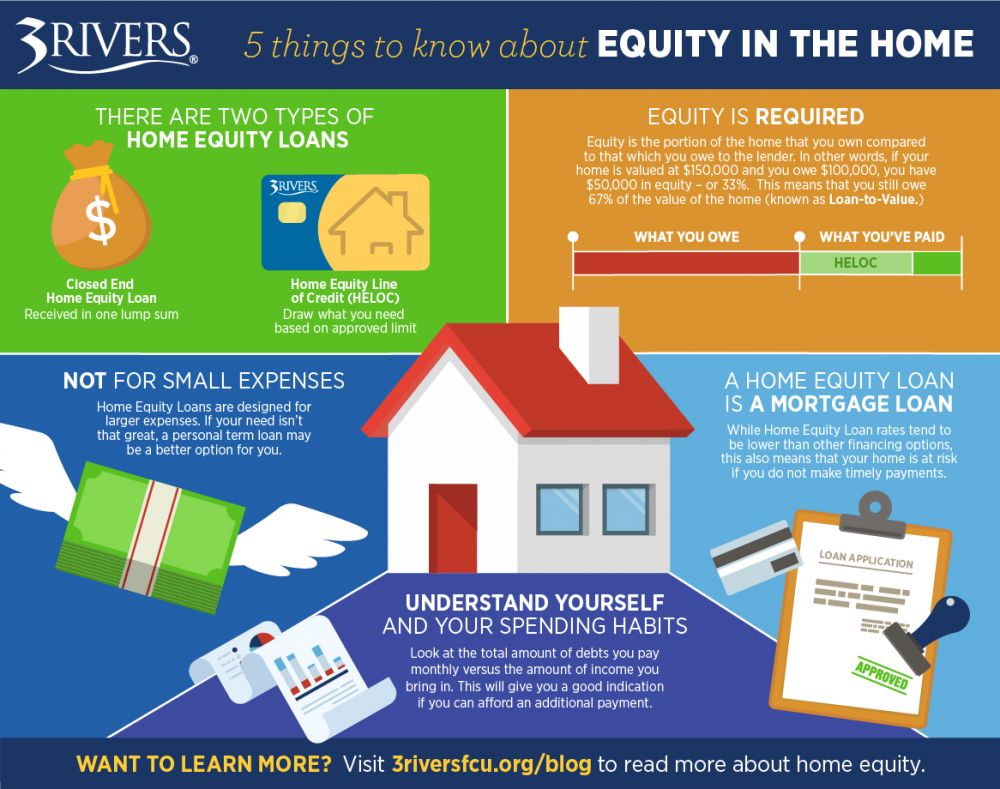
One among them is a property equity financing. Imagine if which you ordered the house to possess $600,000 and just have paid down the mortgage balance as a result of $two hundred,000. Brand new house’s worthy of provides enjoyed to $800,000, for example you really have $640,000 within the equity (the difference between the new appraised really worth as well as the mortgage balance due). If your home is within the a giant urban area into the Canada, primary lenders will generally let you remove all in all, 80% of the home’s collateral within the finance. Therefore, your debts of $2 hundred,000 would nonetheless leave you $440,000 into the credit room, since the then chances are you manage have $two hundred,000 (20%) inside the collateral. Private loan providers in addition will generally max aside in the 75-85% when you look at the come across urban teams, and you can 65-70% in pick outlying communities.
Needless to say, you don’t need to take-out the maximum amount. While we want to have the money available to you quickly without the need to begin repaying interest into the a lump sum financing, it’s also possible to open what is entitled a house guarantee range from credit (HELOC). Believe a credit card using your own house’s guarantee as the offered equilibrium. Oftentimes, you’ve got a draw months when you can access so it line of credit. After brand new draw months, for folks who have not put the money, you never owe people appeal or prominent. When you have utilized a few of the money, you have to begin making money with the dominant and you can notice but just on what you really made use of, perhaps not the amount where you was indeed accepted.

دیدگاهها