When you’re an experienced otherwise effective military having good Virtual personal loans in Nevada assistant-backed financial, there are two main ways to take advantage of over the years reduced re-finance rates: if you take out an interest rate Cures Refinance mortgage (IRRRL) otherwise by using out an earnings-away refinance loan. Per provides their positives and negatives, however, both can also be get you really serious monthly savings if you be eligible for a beneficial interest.
Refinancing The Va-Supported Mortgage
- What is actually a Virtual assistant Home loan Refinance?
- Whenever Is a beneficial Va Home loan Refinance Beneficial?
- Interest Reduction Refinance loan
- VA-Recognized, Cash-Away Re-finance
- Second Tips
What is actually good Virtual assistant Financial Re-finance?
Like most mortgage, mortgages supported by the U.S. Department off Veterans Factors (VA) will likely be refinanced to find best loan terminology-and additionally a diminished rate of interest, which means that cheaper monthly premiums and cash stored on much time manage.
Rates has reached a practically all-day lower. If you have an effective Virtual assistant mortgage together with math renders feel, it is rather great for re-finance, says Draw Reyes, CFP, monetary pointers pro from the Albert, an automatic currency administration and you can investing app. Reyes factors to the present day rates of interest (by ) anywhere between dos.5% to 3% getting fifteen- and you can 31-season repaired-speed mortgages.
Whenever Is actually good Va Financial Refinance Worth it?
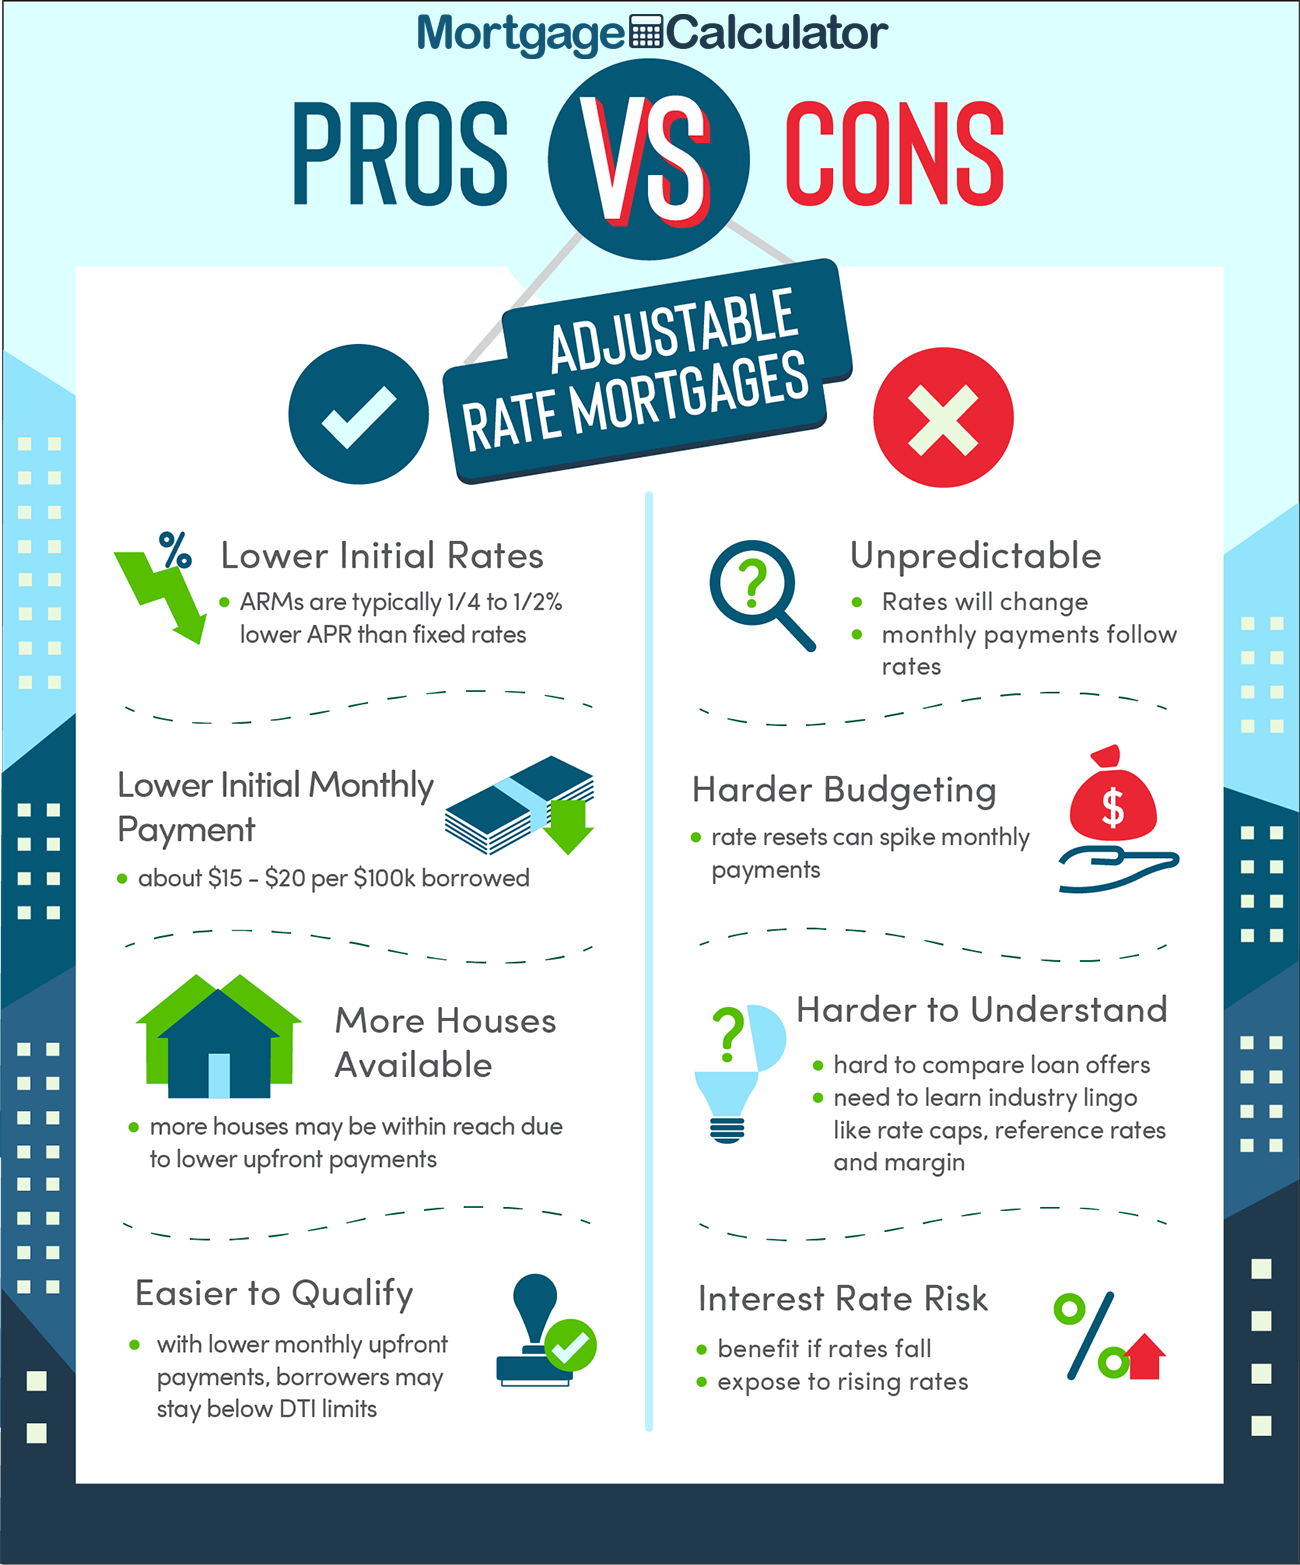
You to definitely such as for instance when it will make experience about how to believe that one is when you have solid borrowing from the bank. Generally speaking, loan providers provide significantly more beneficial refinance prices to people that have a steady income, a track record of responsible credit play with, and you may a decreased loans-to-income ratio. If you keeps a strong borrowing from the bank reputation and will secure lower rates, this can be a worthwhile selection for your.
One more thing to believe: Consider the length of time you intend on residing in your residence. What if We knew I found myself getting a permanent change from route to another, says Eric Bronnenkant, direct regarding tax at Improvement, an effective robo-advisor an internet-based financial, and you may an experienced themselves. Which can be an excellent counterargument to possess doing it. Knowing with cousin certainty that you’re going to become effectively obligated to flow, then it might not build as often financial feel [so you can re-finance your residence].
What is actually mortgage Reduction Refinance mortgage (IRRRL)?
One re-finance choice, for those who have a good Virtual assistant-backed loan, is an interest rate Cures Refinance loan (IRRRL). Also known as a streamline refinance, a keen IRRRL enables you to re-finance your own Va-recognized home loan locate a probably straight down interest rate otherwise option off a variable price to help you a fixed price. Even if an enthusiastic IRRRL try backed by the fresh Virtual assistant, you would have the loan regarding a financial, borrowing from the bank partnership, or any other financial.
Exactly what are the Great things about an excellent Va IRRRL Re-finance?
Having an enthusiastic IRRRL – and other Va financing – you may not need to pay private home loan insurance rates (PMI), which is typically between $30 to help you $70 30 days per $one hundred,one hundred thousand to the home loan, according to Freddie Mac. Most old-fashioned loan providers require that you pay PMI if one makes a down-payment which is lower than 20% of residence’s worthy of.
Various other brighten regarding an enthusiastic IRRRL is you need not render much documents. As opposed to a money-out refinance, the factors for paperwork are much down to own an enthusiastic IRRRL, states Bronnenkant. Generally, loan providers requires you to definitely bring documents to prove the income, assets, and you may loans your notice-report about the program, in order to be sure the creditworthiness. Which have a keen IRRRL, the responsibility from research is significantly all the way down, thin software techniques now is easier.
Expert Tip
If you are using the money away from a funds-aside refinance to alter their home’s worth, you could subtract the borrowed funds appeal – doing $750,100000, in fact.

دیدگاهها